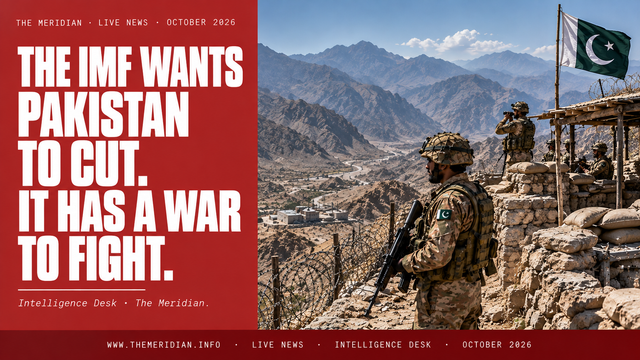
The IMF Wants Pakistan to Cut. Pakistan Has a War to Fight.
Pakistan: 50% of the federal budget on debt service. An active IMF programme demanding fiscal consolidation. A land war on the Afghan border consuming defence allocations faster than parliament can approve them. The Fund wants cuts. The war wants money. Something has to give. It will not be the IMF.

They Burned the Food. 23,000 People Were Waiting for It.
Three WFP trucks burned south of El Fasher on 4 October. 18 tonnes of food destroyed. 23,000 people in Zamzam famine camp were waiting for it. The WFP called it deliberate. OCHA has documented 87 attacks on humanitarian assets in Sudan since April 2023. No investigation has been opened. No government acted on the word the WFP used.

The World's Oil Has Two Doors. Both Are Closing.
Hormuz and Bab el-Mandab handle 35% of global seaborne crude. Both are under simultaneous pressure for the first time. 95% of container ships are already rerouting via the Cape of Good Hope. Each rerouted VLCC adds $1.5 million in voyage cost. Pakistan, Sri Lanka and Mauritius have no alternative. They pay more, or they go without.

What Does Putin Really Want?
Born Leningrad 1952. His brother died in the Siege. KGB career. Watched the Soviet collapse from Dresden. GDP growth 3.6% in 2026. Unemployment below 3%. Life expectancy 67 years. Democracy Index 144th. 700,000 emigrated in 2022. Elected 87.28% in March 2024. He would like you to know he is very comfortable.

The World Borrowed $348 Trillion
$348 trillion. Five decades of unconstrained borrowing built the modern world. The bill is arriving. Not for those who borrowed without consequence, but for those who had no say in the terms. Vayu Putra opens the October 2026 edition.

1971: The Day the World Started Borrowing Without Limits
15 August 1971. Nixon closed the gold window. The dollar's anchor to a fixed commodity was severed. The constraint on government borrowing became political, not monetary. In the 55 years since, global debt has risen from roughly $20 trillion to $348 trillion. One decision. Five decades of consequence.

The Debt That Built the Modern World
Hospitals. Universities. Welfare states. Interstate highways. The internet. Much of what is called civilisation was built on borrowed money. The question is not whether debt is bad. The question is who repays it, and whether that has ever been the same people who decided to borrow.

The Four Creditors Who Own the World
Central banks. Commercial banks. Asset managers. Bilateral state creditors. Four categories. Four different interests. Four different leverage mechanisms. Who holds what, what each wants, and what happens when a country cannot pay.

China's $1 Trillion Debt Trap: Myth and Reality
China holds approximately $1 trillion in sovereign lending across the Global South. The debt trap narrative is the Western account. The evidence is more complicated. What Beijing actually holds, what it has restructured, and what the leverage actually looks like in 2026.

BlackRock Owns Your Government's Debt. Here Is What That Means.
BlackRock manages over $10 trillion in assets. A significant share is sovereign debt. It does not campaign. It does not legislate. It reprices. The September 2022 UK gilt crisis showed exactly what happens when the bond market and a democratic mandate conflict.

India's $127 Billion Diaspora Gamble: The Fifth Option
RBI FCNR(B) deposits: $127.226 billion as at September 2026. In 2013, India raised $34 billion from its diaspora in 60 days without approaching the IMF. The fifth option for sovereign financing that most countries have never built. Here is why India could and why others cannot easily copy it.

The IMF: Lender of Last Resort or Instrument of Creditor Power?
Ghana must devalue the cedi. Sri Lanka must devalue the rupee. Pakistan must devalue the rupee. The UK never devalued the pound. The US never devalued the dollar. The IMF applies currency discipline exclusively to countries that did not design the system. Here is the architecture, the record, and the surcharge that penalises the most distressed.

When America Cuts, It Chooses. When Ghana Cuts, It Has No Choice.
The UK had austerity after 2010. America had spending cuts. But nobody required them as a condition of survival. Pakistan spends 50% of its budget on debt service before a rupee reaches a school. The distinction between sovereign austerity and imposed austerity is the asymmetry this edition is built around.

The CFA Franc: How 14 African Countries Finance the ECB and Nobody Talks About It
14 countries. 180 million people. 50% of their foreign exchange reserves held in the French Treasury. The CFA franc was created in 1945. The Eco currency was announced in 2019. It has not launched. The arrangement continues. Here is exactly how it works and what it costs.

Interest Rates for the Global South: Why the Same Debt Costs Four Times as Much
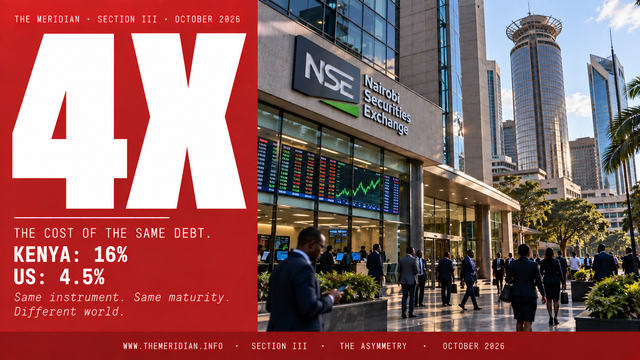
Kenya issues at 16%. The US issues at 4.5%. Same instrument. Same maturity. $2.3 billion extra in interest on every $1 billion borrowed. The gap is not risk. It is original sin, the reserve currency effect, and a credit rating methodology that penalises countries for not being rich.

Odious Debt: The Debt the Global South Was Never Asked to Borrow
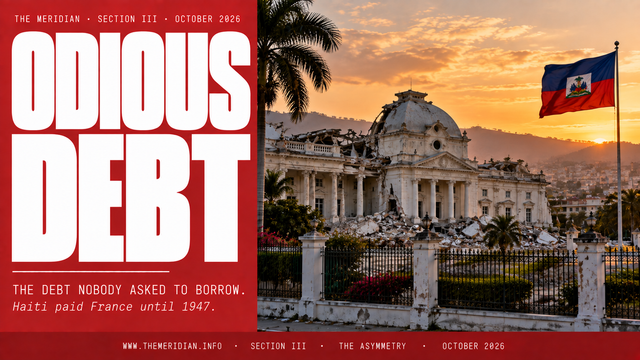
Haiti paid France until 1947 for the cost of its own freedom. 122 years. The doctrine of odious debt has existed in international law since 1927. No court has ever applied it. Here is the Haiti case in full, the apartheid South Africa case, Iraq 2003, and why the doctrine that exists in law has never been used.

The United States: The Exorbitant Privilege Is Running Out
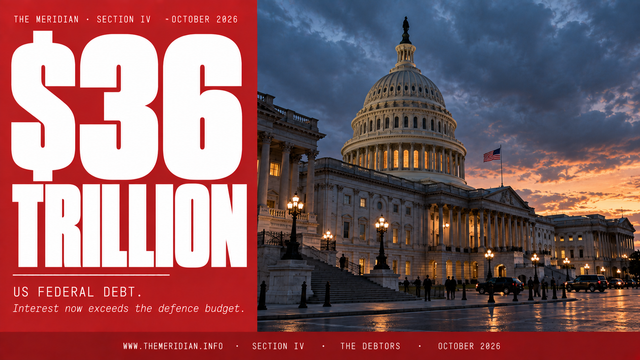
$36 trillion in federal debt. Interest payments in FY2026 exceeded the entire defence budget for the first time. The privilege is real but not unlimited. Moody's downgraded. The market barely moved. Here are the three scenarios for how the privilege unwinds.

Japan: The Laboratory of Debt
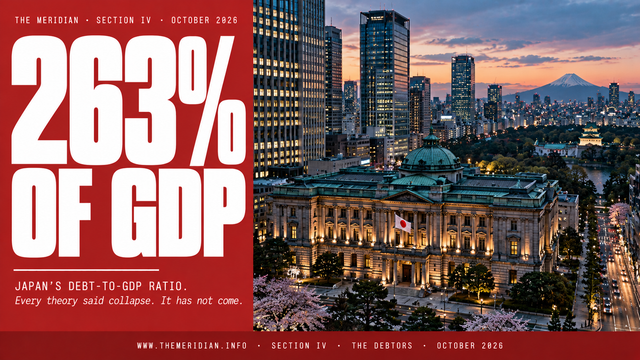
263% debt-to-GDP. No default. No crisis. Japan was the first country in history to implement quantitative easing, in March 2001, seven years before the Fed copied it. Every theory predicted collapse. The laboratory has results. Here is what they actually prove -- and why they do not travel.

France: The Social Contract and the Bond Market
112% of GDP. Deficit 5.1%. Under EU Excessive Deficit Procedure. OAT-Bund spread at 70-80 basis points and widening. The pension reform passed without a parliamentary vote and produced months of strikes. The bond market and the social contract are on a collision course. One of them will eventually move.

Italy: The Trap at the Heart of Europe
140% of GDP. 0.2% average annual growth for two decades. A banking system holding 400-500 billion euros in Italian government bonds. Cannot devalue. Cannot default without a European banking crisis. Cannot grow fast enough to reduce the ratio. Too big to fail. Too big to save.

Argentina: Nine Defaults and Still Borrowing
Nine defaults since 1827. The 2001 collapse was the largest sovereign default in history at the time. Milei achieved a fiscal surplus and cut inflation from 211%. Creditors forgot and lent again. The architecture of the cycle, what produces it, and why both sides of it keep showing up.

Sri Lanka: What Collapse Actually Looks Like
April 2022. Usable reserves below $50 million -- less than a single day of fuel imports. Petrol queues for miles. Hospitals out of medicine. The president fled. The three triggers that activated simultaneously, the $12 billion in commercial bonds, and what it means for every small open economy carrying external debt.

Kenya: The IMF Programme That Started a Revolution
June 2024. An IMF-backed Finance Bill taxed bread, cooking oil, sanitary products. Parliament stormed. At least 39 killed. Ruto withdrew the bill on television. The IMF programme continued. The debt remained. 37% of revenues go to debt service before a shilling reaches a school. The live case where imposed austerity meets democratic resistance.

Britain: No Growth Since 2008. No Plan Since 2022. The Debt Keeps Rising.
Productivity flat since 2008. The gilt market panicked in September 2022 and required £65 billion in emergency Bank of England purchases. Annual borrowing and annual interest payments both approximately £100 billion. The structural conditions that no government has confronted and the deferred reckoning that compounds each year.

Austerity: The Cost Paid by Those Who Did Not Borrow
Greece: pensions cut 40-50%. Pakistan: 1.2% of GDP on health. Ghana: workers' pension funds restructured as IMF condition. The IMF's own researchers wrote in 2016 that austerity increases inequality. The programme conditions continued unchanged. The cost falls on the same people every time.

Inflation: The Invisible Tax
No parliament votes for it. Inflation reduces the real value of sovereign debt while destroying the real value of wages and savings. UK real wages fell 3-4% in 2022. Zimbabwe hit 79.6 billion percent. The Global South's inflation experience is categorically different. The political economy of who monetary policy actually serves.

Default: The Option Nobody Wants to Name
Default is not chosen. It is reached. Argentina: nine times. Zambia: 3 years to restructure under the G20 Common Framework. NML Capital bought Argentine bonds at 20 cents and extracted face value. The holdout problem, the G20 framework gap, and why naming default early often costs less than the austerity applied to avoid it.

The Debt Jubilee: The Radical Idea Whose Time Is Coming
Leviticus 25: every 50 years, debts are cancelled. HIPC cancelled $130 billion from 40 countries with structural adjustment as the price. Many re-accumulated the debt within two decades. The architecture was not cancelled. Only the debt was. The arithmetic case for jubilee in 2026 -- and why the structure must go with it.

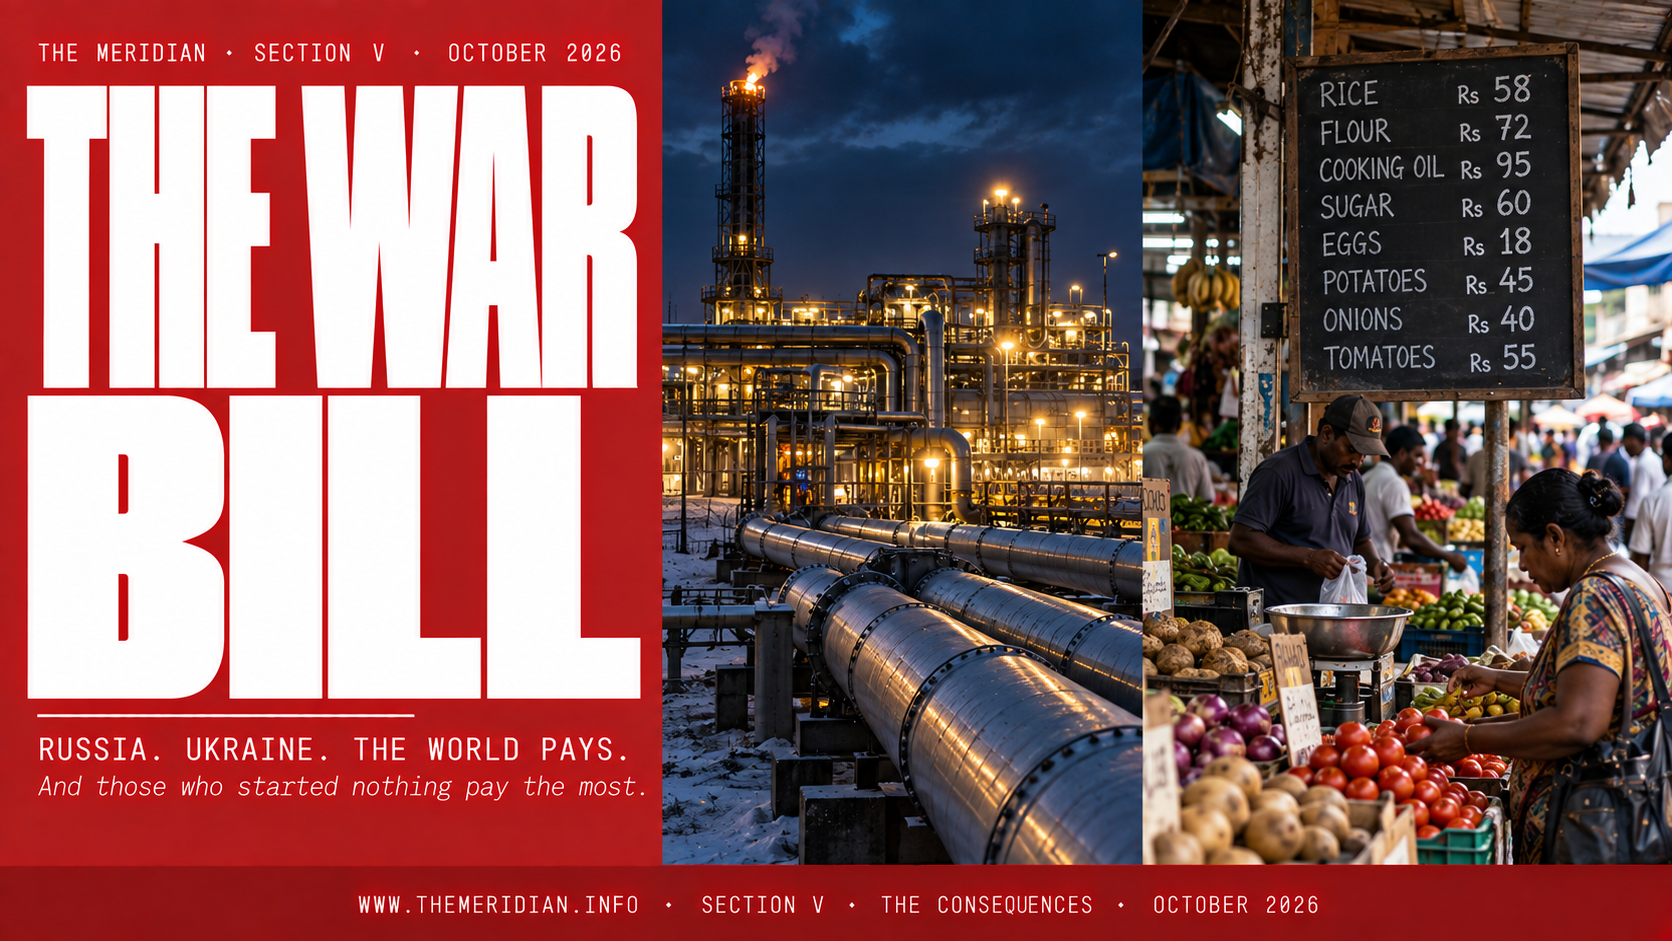
The War That Made Everyone Poorer
European gas prices hit 340 EUR/MWh. The FAO Food Price Index hit its highest level on record. Russia and Ukraine: 30% of global wheat, 65% of sunflower oil. The Global South's additional food import bill: $100-120 billion. Countries that started nothing paid the most. The war's full fiscal legacy.

AI. Debt. War. El Niño. Energy Crisis. Unemployment. Are Any Governments Ready?
Six structural crises are arriving simultaneously and each makes the others worse. No government has a credible plan for all six at once. This essay names the trap and the only exit that survives arithmetic scrutiny.

The Reckoning: A Closing Essay
$348 trillion. The architecture that produced it. The asymmetry that governs it. Six propositions for what must change. The nurse in Pakistan. The pensioner in Ghana. The student in Kenya. The patient in Greece. None of them designed the architecture. All of them are paying for it. The reckoning does not arrive all at once. But it arrives.
Tin Tuna Index
A tin of tuna is a small purchase. The time required to afford it reveals a much larger truth. The Tin Tuna Index measures how many minutes of minimum-wage labour are required to buy one standard tin of tuna.
In richer labour markets, tuna remains a routine protein purchase. In lower-wage economies, it can absorb hours of labour. That difference reveals how wages convert into nutrition, resilience and everyday dignity.
A Simpler Reading of Food Affordability
The Tin Tuna Index begins from a practical human question rather than an aggregate economic one. It asks how much time a worker on minimum pay must exchange for a basic tin of protein, and in doing so converts wage systems into something immediate, legible and socially revealing.
Why Tuna
Tuna is globally traded, nutritionally meaningful and tied directly to marine extraction, processing, shipping and retail pricing. It is small enough to feel ordinary, yet powerful enough to reveal the wage-food relationship clearly.
Why Time Worked
Time is the most human denominator in the economy. Measuring minutes worked rather than simply price turns a commodity into a direct test of dignity, purchasing power and everyday economic reality.
Why It Matters
A tin that costs six minutes of labour in one country and several hours in another is not just a retail difference. It exposes the uneven translation of work into nutrition, resilience and access.
How to Read It
Lower readings indicate broad affordability. Higher readings show that protein access is becoming structurally burdensome, pushing a routine purchase into the realm of visible household strain.
Featured Country Briefings
In richer labour markets, tuna remains a small retail decision measured in minutes. In lower-wage economies, it begins to absorb hours of labour and shifts from everyday protein to constrained purchase.
🇺🇸 United States
🇲🇺 Mauritius
🇰🇪 Kenya
Affordability Bands
Grouped institutionally, countries fall into four broad bands: low burden, moderate, high and extreme. This makes the time-cost pattern easier to interpret across very different labour markets.
Low Burden
Tuna remains a routine protein purchase, typically affordable within a short span of paid labour.
Moderate
Tuna remains affordable, but no longer frictionless. It becomes visible within the household budget.
High
Tuna begins to shift from routine purchase to budgeted item, indicating noticeable affordability strain.
Extreme
Tuna becomes a structurally burdensome purchase, measured in hours rather than minutes of work.
Tin Tuna Index Rankings
The table below ranks selected economies by the estimated time required for a minimum-wage worker to afford one standard tin of tuna. Lower readings indicate stronger affordability. Higher readings indicate greater food-access strain and a weaker conversion of labour into nutrition.
| Rank | Economy | Time Worked | Minutes | Affordability Tier | Interpretation |
|---|---|---|---|---|---|
| 1 | 🇬🇧 United Kingdom | 6 min | 6 | Low | Routine protein purchase with minimal labour burden. |
| 2 | 🇩🇪 Germany | 8 min | 8 | Low | Discount retail pricing and stronger wages preserve affordability. |
| 3 | 🇫🇷 France | 9 min | 9 | Low | Basic tuna remains broadly accessible within the wage floor. |
| 4 | 🇦🇺 Australia | 10 min | 10 | Low | Tuna remains an ordinary purchase in time-cost terms. |
| 5 | 🇨🇦 Canada | 12 min | 12 | Low | Protein access remains relatively easy across wage floors. |
| 6 | 🇺🇸 United States | 15 min | 15 | Moderate | Still broadly affordable, though not as frictionless as the UK benchmark. |
| 7 | 🇯🇵 Japan | 18 min | 18 | Moderate | Accessible, but increasingly visible within household budgeting. |
| 8 | 🇰🇷 South Korea | 20 min | 20 | Moderate | Affordable, though no longer trivial in wage-to-food terms. |
| 9 | 🇨🇱 Chile | 22 min | 22 | Moderate | The burden remains manageable but clearly visible. |
| 10 | 🇵🇱 Poland | 25 min | 25 | Moderate | Tuna is affordable, but no longer an invisible purchase. |
| 11 | 🇲🇾 Malaysia | 28 min | 28 | Moderate | Below one hour, but far less easy than in advanced wage economies. |
| 12 | 🇲🇺 Mauritius | 30 min | 30 | Moderate | A processing hub where production and affordability diverge. |
| 13 | 🇿🇦 South Africa | 35 min | 35 | High | The time cost begins to signal broader food-access strain. |
| 14 | 🇹🇭 Thailand | 40 min | 40 | High | Tuna shifts from ordinary good to budgeted purchase. |
| 15 | 🇵🇭 Philippines | 55 min | 55 | High | Approaching one hour of labour for one tin indicates real pressure. |
| 16 | 🇮🇩 Indonesia | 65 min | 65 | High | Protein access becomes visibly constrained within the wage floor. |
| 17 | 🇮🇳 India | 90 min | 90 | High | Imported tuna remains expensive relative to many minimum-wage settings. |
| 18 | 🇰🇪 Kenya | 150 min | 150 | Extreme | Basic tinned fish absorbs a substantial share of a day’s lower-paid labour. |
| 19 | 🇳🇬 Nigeria | 210 min | 210 | Extreme | The commodity transitions from everyday good to meaningful budget strain. |
| 20 | 🇧🇩 Bangladesh | 240 min | 240 | Extreme | Imported tuna behaves as a premium purchase, far from routine worker affordability. |
| 21 | 🇵🇰 Pakistan | 270 min | 270 | Extreme | High import cost relative to wages pushes tuna beyond routine consumption. |
| 22 | 🇪🇹 Ethiopia | 360 min | 360 | Extreme | A single canned fish purchase reflects structural exclusion rather than ordinary market choice. |
Tin Tuna Calculator
Enter an hourly wage and the retail price of one tin of tuna. The calculator estimates the minutes of labour required, the equivalent in hours, and the affordability tier.
What the Index Implies for Policy
The disparities revealed by the Tin Tuna Index are not random market outcomes. They are shaped by wage systems, tariff structures, labour standards, logistics, import dependence and the distribution of value within global supply chains.
Immediate Interventions
Port-state labour inspections, wage floor enforcement in processing zones, and targeted food-security support for workers facing high protein time-costs.
Medium-Term Reforms
Tariff reform, domestic value-add incentives, and procurement strategies that lower the cost of basic protein without suppressing wage growth.
Long-Term Transformation
Human-welfare-first economic design, stronger bargaining power for labour, and resource-sovereignty models that link marine wealth to domestic nutrition outcomes.
The Future of Ocean Equity
Climate stress, concentration in shipping and processing, and rising food demand all threaten to increase tuna prices faster than wage floors in lower-income economies can adjust.
The Tin Tuna Index is not just about tuna. It is about whether labour still buys nutrition in a world built on trade, extraction and uneven power.
Methodology (how the index is computed)
Metric: minutes of legal minimum-wage labour required to purchase one standard tin of tuna.
Formula: (Tuna price / Hourly wage) × 60.
Steps: (1) identify the statutory minimum wage or closest legal wage floor; (2) identify the cheapest widely available retail price for a comparable tin; (3) convert to minutes worked; (4) scale if pack size differs; (5) note promotional pricing where relevant.
Interpretation: Lower values indicate stronger affordability. Higher values indicate greater food-access strain and a weaker conversion of labour into nutrition.
Boundary: The index is designed as a practical affordability benchmark, not a full cost-of-living basket or nutritional index.
Related Index and Research Pages
The Tin Tuna Index sits within a wider editorial architecture of affordability experiments, composite indicators, country intelligence and long-form analysis.
Mind Economy Indices
Composite indicators for human intelligence, public priorities, fiscal strain and youth opportunity across the Global South.
UN46 Reports
Least-developed-country dossiers built around fragility, export dependence, institutional weakness and human pressure.
Dispatches
Long-form political, economic and philosophical reporting across the Global South and beyond.